
Emergency Financial Aid for College Students Who Need Help Fast
Get emergency financial aid for college students who need help fast. Learn campus grants, federal options, and quick scholarships that disburse in days.
By David Reynolds
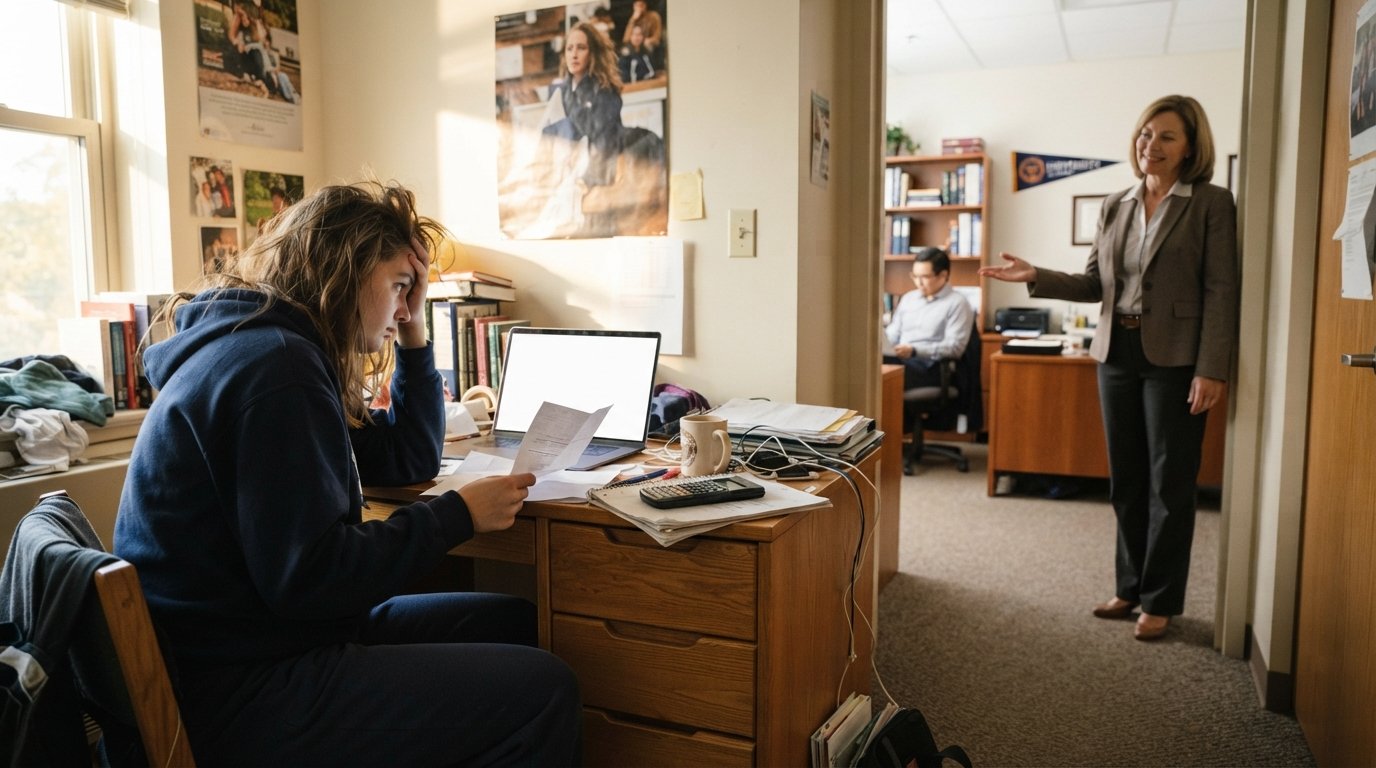
A tuition payment posts to your student account at 8:00 a.m. on a Tuesday, and by 8:15 you are staring at a balance you cannot cover. Maybe a parent lost a job, a car repair wiped out your savings, or a financial aid disbursement came in smaller than expected. When money runs out mid-semester, the pressure is immediate, and dropping out can feel like the only option. It is not. Colleges, government programs, and private organizations all maintain emergency funds designed for exactly this situation, and most students never ask because they do not know these programs exist.
This guide walks through the fastest legitimate ways to secure emergency financial aid for college students who need help fast, from same-day campus grants to federal options and community resources. You will learn which offices to contact first, what documents to prepare, and how to frame a request so it gets approved instead of buried in a queue.
Start With Your College's Emergency Aid Office
The single fastest source of emergency money is usually sitting on your own campus. Nearly every accredited college and university in the United States operates some form of student emergency fund, and many have expanded these programs since 2020 with support from federal COVID relief legislation and private donors. These funds exist specifically for students facing sudden hardship, and they are often designed to disburse within days, not weeks.
The office that manages this money varies by school. At large universities, it is typically the Dean of Students office, the Student Affairs division, or a dedicated Student Emergency Fund portal. At community colleges, the financial aid office or a student resource center usually handles it. Before you call anyone, check your school's website and search for terms like "student emergency fund," "hardship grant," or "student relief." Many schools have a simple online application that takes 15 to 30 minutes to complete.
When you apply, be specific and factual about your situation. Vague requests slow down review. State the exact amount you need, what it covers (rent, textbooks, a medical bill, transportation), and when you need it. Attach documentation if you have it: an eviction notice, a medical bill, a layoff letter, a car repair estimate. Committees review dozens of applications, and the ones with clear, documented need move fastest.
Here is what a typical campus emergency aid process looks like, so you know what to expect:
- Locate the emergency fund application on your school's website or ask the Dean of Students office directly.
- Complete the short application, stating the amount needed and the specific hardship.
- Submit supporting documents (bills, notices, or a brief statement from a trusted staff member).
- Attend a brief interview or phone call if the committee requests one.
- Receive funds via direct deposit or a campus debit card, often within 2 to 5 business days.
Awards from campus emergency funds typically range from $200 to $2,000, and most do not require repayment because they are grants, not loans. Some schools cap awards per student per academic year, so ask about limits if you may need help more than once. If your school does not have a fund, ask the financial aid office about partnerships with organizations like the Hope Center or the California Community Colleges' basic needs programs, which often extend support beyond their home states.
One more note: do not assume you will be denied because you already receive financial aid. Emergency funds are separate from need-based aid packages, and receiving Pell Grants or loans does not disqualify you. In fact, students who already demonstrate financial need are often prioritized.
Federal and State Options That Can Move Quickly
If your campus fund is exhausted or unavailable, federal and state programs can fill the gap, though timelines vary. The most direct federal option is the Federal Supplemental Educational Opportunity Grant (FSEOG), which is administered by your school's financial aid office and reserved for students with exceptional need. Unlike Pell Grants, FSEOG funds are limited and distributed on a first-come, first-served basis, so ask early in the term, not after your account goes negative.
For students who need cash within days, a federal Direct Subsidized Loan disbursement may be the fastest large-dollar option, but it requires your school to process a loan adjustment, which can take one to three weeks. If you have not yet accepted your loans for the term, contact the financial aid office immediately and ask whether a mid-semester disbursement is possible. Some schools can expedite this if you explain the hardship.
State programs vary widely but are worth checking. Many states run emergency assistance funds for students in specific situations, such as foster youth, veterans, or students experiencing homelessness. Your state's higher education agency or a quick call to 211 (the national social services hotline) can point you to options. Some states also allow students to apply for emergency SNAP benefits (food assistance) within days, which frees up cash for other bills.
Keep in mind that federal aid rules require your school to disburse funds by certain deadlines, and emergency requests outside the normal cycle may need special approval. Be persistent but polite, and follow up in writing so you have a record. If you want a broader overview of how to layer scholarships, grants, and loans strategically, our guide on maximize scholarships and financial aid for college students explains how to build a funding plan that reduces the chance of a mid-semester crisis.
Scholarships and Grants With Fast Turnaround
Scholarships are usually associated with long application cycles, but a surprising number of small awards have quick turnarounds, especially those designed for emergency situations. The key is to target niche scholarships with low applicant pools and rolling deadlines. A $500 scholarship from a local rotary club or a professional association may be easier to win than a national $10,000 award, and the money can arrive within weeks.
Several national organizations specialize in emergency aid for students. The Dream.US, Scholarship America, and the United Negro College Fund all offer emergency grants for eligible students, often with simplified applications. The Hope Center for College, Community, and Justice maintains a directory of emergency aid programs by state. Your school's scholarship office may also keep a list of fast-turnaround awards that do not appear on public databases.
When you apply for emergency scholarships, prioritize these characteristics:
- Rolling or monthly deadlines rather than annual cycles
- Awards under $2,000, which often have fewer applicants
- Local or identity-based eligibility (your hometown, major, or background)
- Applications that do not require recommendation letters, which slow things down
If you are an adult learner or career changer returning to school, you may qualify for additional emergency funds through workforce development programs or employer tuition assistance. Resources like DegreesOnline.Education provide guidance on accredited online degree programs and financial aid options for working professionals, which can help you find flexible paths that reduce the risk of a financial emergency derailing your education.
Community and Nonprofit Resources That Fill Gaps
When campus and government options are not enough, community organizations often step in. Churches, mosques, synagogues, and community centers frequently maintain discretionary funds for people in crisis, and they typically do not require you to be a member. A quick call to a few local congregations can yield a small grant or a no-interest loan within days.
Nonprofit organizations like Modest Needs, which provides short-term grants to individuals facing unexpected expenses, and the Salvation Army, which offers emergency assistance for rent and utilities, are worth contacting. United Way chapters across the country operate emergency funds and can connect you with local resources through the 211 hotline. These programs usually require proof of income and a copy of the bill you need help with, but they can move quickly once documents are submitted.
Do not overlook mutual aid networks, which have grown on social media and campus forums. A GoFundMe campaign or a request in a Facebook group for your university can raise hundreds of dollars in a day, though it is not a substitute for formal aid. Use crowdfunding as a supplement, not a plan.
Food insecurity is one of the most common hidden costs that drains a student's budget. Campus food pantries, SNAP benefits, and meal swipe donation programs can free up $100 to $300 per month, which may be enough to cover a utility bill or a textbook. The College and University Food Bank Alliance lists hundreds of campus pantries nationwide.
How to Apply So You Get Approved Faster
Speed matters, and the way you present your request can shave days off the process. Whether you are applying for a campus grant, a scholarship, or a nonprofit fund, follow these practices to avoid common delays.
First, gather your documents before you apply. Most emergency aid programs ask for some combination of the following: a copy of your student ID, a recent bill or notice showing the amount due, proof of income (pay stubs or a financial aid award letter), and a brief personal statement. Having these ready means you can submit a complete application in one sitting rather than going back and forth.
Second, be concise and specific in your personal statement. Committees are not looking for a sob story; they are looking for a clear, verifiable need and a realistic plan. For example, instead of writing "I am struggling financially," write "My car transmission failed last week, and the $1,200 repair is beyond my budget. I need $600 to cover the remaining balance so I can continue driving to my clinical rotation." Specificity signals credibility.
Third, apply to multiple sources at once. There is no rule against receiving aid from more than one program, though some funds require you to disclose other awards. Applying to three or four options increases your odds of getting at least one yes quickly. Keep a simple spreadsheet tracking what you applied for, the amount requested, the date submitted, and the expected response time.
Fourth, follow up. A polite email or phone call one or two days after submitting can move your application to the top of the pile, especially at understaffed offices. If you are denied, ask why and whether you can reapply with additional documentation. Many denials are due to incomplete applications, not lack of need.
Finally, know your rights and your school's obligations. If you receive federal financial aid, your school must provide a way to appeal or request a professional judgment adjustment if your circumstances have changed since you filed the FAFSA. A job loss, a medical emergency, or a death in the family can qualify you for more aid even mid-year. The financial aid office can adjust your cost of attendance or your expected family contribution, which may unlock additional grant or loan funds.
Protect Yourself From Predatory Options
When money is tight, high-interest payday loans and cash advance apps can look tempting, but they often trap students in a cycle of debt that makes the original problem worse. A $200 payday loan can carry an annual percentage rate above 300 percent, and repayment is typically due on your next payday, which may be weeks away. Avoid these products if at all possible.
Similarly, be cautious of any "emergency scholarship" that requires an upfront fee to apply. Legitimate aid programs never charge you to submit an application. If a website asks for your credit card number or a processing fee, walk away. You can verify a scholarship's legitimacy through your school's financial aid office or the Better Business Bureau.
If you must borrow, prioritize federal student loans over private ones. Federal loans offer income-driven repayment, deferment, and forgiveness options that private loans rarely match. A mid-semester federal loan disbursement, while not instant, is far safer than a private emergency loan with variable interest and no flexibility.
It also helps to build a small emergency buffer for the future, even $10 a week, so the next crisis does not derail your semester. Many campuses offer financial literacy workshops that teach budgeting and savings strategies tailored to students. These skills pay off long after graduation.
Financial emergencies happen to students from every background, and needing help does not mean you failed. It means you are navigating a system that is complex by design. The key is to act quickly, ask specifically, and use every legitimate resource available. Start with your campus emergency fund, layer in federal and state options, and fill remaining gaps with scholarships and community aid. With the right approach, you can keep your education on track and focus on what matters: finishing your degree.