
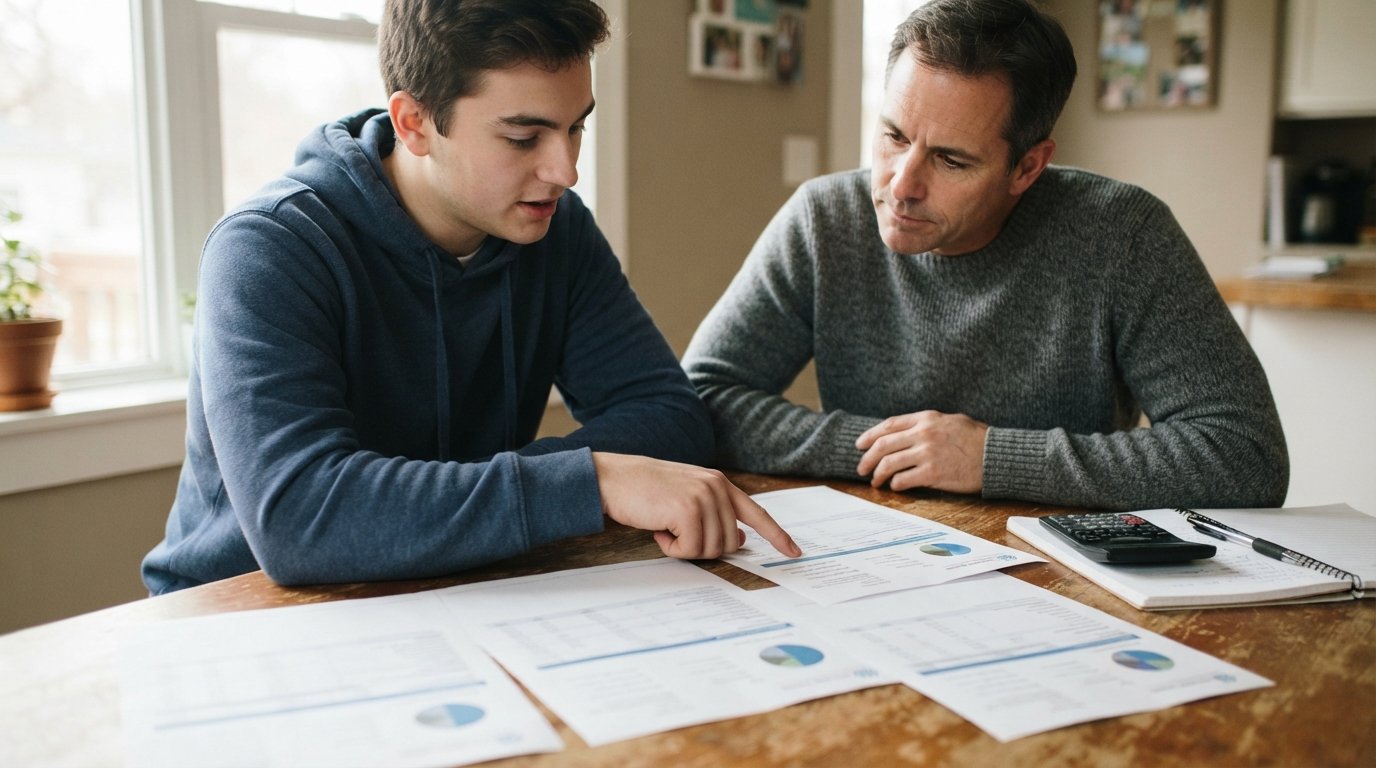
How to Read College Financial Aid Award Letters Side by Side
Learn how to read college financial aid award letters side by side to uncover the true cost of each offer and avoid costly surprises.
By Andrew Wilson
You have just received a stack of financial aid award letters from colleges, and at first glance, they all look generous. One school promises a $40,000 package, another offers $32,000, and a third mentions $28,000. But before you celebrate or panic, know this: award letters are not standardized. The numbers can be presented in ways that make offers seem more valuable than they are. Learning how to read college financial aid award letters side by side is the single most effective way to cut through the confusion, compare apples to apples, and avoid a financial surprise later. This guide gives you a practical, repeatable method to line up offers from multiple schools and see which one is truly the most affordable for your family.
Why Side-by-Side Comparison Is Essential
Colleges are not required to use a uniform format for award letters. Some schools group all aid together, while others separate gift aid from self-help aid. Some use vague labels like "institutional grant" without explaining whether it is need-based or merit-based. Others bury loan eligibility in the middle of the letter, making it look like part of the package. When you read each letter in isolation, it is easy to focus on the bottom-line total and assume the largest number is the best deal. That assumption is often wrong.
Side-by-side comparison forces you to normalize the data. By placing each school's award components in the same order and using the same categories, you can see exactly which offers are composed of free money (grants and scholarships) versus borrowed money (loans) and earned money (work-study). This process reveals the true out-of-pocket cost for each school and helps you make an informed decision that aligns with your family's finances. It also gives you a solid basis for appealing an offer if you find that another school has provided a better package for a comparable education.
Before you begin, gather all award letters, your Student Aid Report (SAR) from the FAFSA, and any supplemental documents from the colleges. Set up a spreadsheet or a large table where you can list each school across the top and the aid categories down the left side. This visual layout is the foundation of a side-by-side review. For a broader planning framework that complements this process, see our college financial planning checklist to ensure you are covering all the necessary steps.
Key Lines That Commonly Differ Between Award Letters
Not every line on an award letter carries the same weight. Some items are straightforward, while others are prone to variation in labeling and presentation. When comparing offers, pay close attention to the following categories, as they are the ones most likely to differ and most likely to affect your bottom line.
- Grants and scholarships: These are gift aid and do not need to be repaid. However, some letters combine need-based and merit-based grants under a single heading, while others separate them. Check whether grants are guaranteed for all four years or just the first year.
- Loans: Federal student loans, including Direct Subsidized and Unsubsidized loans, are often listed as part of the award package. These are borrowed funds and must be repaid with interest. Some letters also list Parent PLUS loans or private loans, which are additional debt options, not free aid.
- Work-study: This is earned money that you receive through a campus job. It is not applied directly to your tuition bill upfront, so it should be treated separately from grant aid when calculating your immediate costs.
- Cost of attendance (COA): Each school calculates its COA differently. Some include travel and personal expenses, while others list only direct costs. Make sure you compare the total COA, not just tuition and fees.
- Unmet need: This is the gap between the COA and the aid offered. A school may meet 100% of your demonstrated need, while another meets only 80%. The unmet need is what you or your family will be responsible for covering through savings, additional loans, or other resources.
Understanding these differences is crucial. For example, a school that offers a $50,000 package might include $10,000 in loans and $5,000 in work-study, leaving $35,000 in grants. Another school might offer $45,000 with $40,000 in grants and only $5,000 in loans. The second package is actually more valuable because it contains more free money and less debt. Without a side-by-side view, you might mistakenly favor the larger total package.
Another common variation is the treatment of outside scholarships. Some colleges reduce their own grant aid when you receive an outside scholarship, a practice known as "overawarding." Others allow outside scholarships to reduce your loan or work-study burden first. This policy can significantly impact your net cost, so check each school's policy on outside scholarships.
Distinguishing Grants and Scholarships from Loans and Work-Study
The most important distinction in any award letter is between gift aid and self-help aid. Gift aid, which includes grants and scholarships, is essentially free money that does not need to be repaid. Self-help aid, which includes loans and work-study, requires either repayment with interest or active employment. When comparing offers, your goal is to maximize gift aid and minimize self-help aid.
Grants are typically need-based and come from federal or state governments or from the college itself. Scholarships are usually merit-based and can come from the college, private organizations, or other sources. Both are valuable, but pay attention to the conditions attached. Some scholarships require maintaining a certain GPA or enrolling full-time. If you fail to meet the conditions, you could lose the funding, turning a grant into a future expense.
Loans are a common component of award letters, but they are not all equal. Federal Direct Subsidized loans are preferable to Unsubsidized loans because the government pays the interest while you are in school. Parent PLUS loans and private loans are riskier and often carry higher interest rates. Work-study is earned income, but it is not guaranteed; you must find a qualifying job and work the required hours to receive the funds. When you compare offers, total up the loan amounts and work-study amounts separately from grants. A package with a higher total but a larger loan component may leave you with more debt after graduation.
To make this concrete, create columns in your spreadsheet for "Free Money" (grants + scholarships), "Loans" (subsidized + unsubsidized + PLUS), "Work-Study," and "Unmet Need." Then calculate the net cost for each school by subtracting free money from the total cost of attendance. This net cost figure is the most accurate reflection of what your family will actually pay. For many families, the school with the lowest net cost is the most affordable choice, even if its sticker price is higher.
Questions to Ask When an Award Letter Is Unclear or Inconsistent
Even with a careful side-by-side review, you may encounter award letters that are vague or inconsistent. Do not hesitate to contact the financial aid office for clarification. Asking the right questions can uncover details that significantly affect your decision. Here are some key questions to ask:
- Is this grant or scholarship guaranteed for all four years? Many awards are renewable, but some are for one year only. Ask about the renewal criteria and whether the amount can change if your family's financial circumstances remain the same.
- What is the total cost of attendance, including indirect costs? Ensure you are comparing the full COA, not just tuition. Ask for a breakdown of direct costs (tuition, fees, room, board) and indirect costs (books, supplies, travel, personal expenses).
- How will outside scholarships affect my award? Some schools reduce their own grants, while others reduce loans or work-study. Understanding this policy helps you anticipate any changes if you receive additional scholarships.
- What is the policy on special circumstances? If your family's financial situation has changed since you filed the FAFSA (e.g., job loss, medical expenses), ask about the process for a professional judgment review. This could increase your aid eligibility.
- Are there any conditions or requirements I should know about? Some awards require you to live on campus, enroll in a certain number of credits, or maintain a specific GPA. Clarify these conditions upfront to avoid surprises.
When you call or email, keep a record of your conversations and follow up with a written summary. This documentation can be useful if you need to appeal or if there are discrepancies later. Remember that financial aid offices are there to help; they are accustomed to these questions and can provide detailed explanations. Do not feel intimidated by the process.
If you find that an award letter contains errors or omits information, bring it to the attention of the financial aid office immediately. Mistakes can happen, and correcting them early can prevent problems down the line. In some cases, a simple clarification can lead to a revised offer that better reflects your situation.
How to Appeal or Request Reconsideration When Offers Fall Short
If, after comparing offers side by side, you find that your top-choice school has offered a package that is significantly less generous than a comparable school, you have the option to appeal. Appeals, also known as reconsideration requests, are a formal way to ask the financial aid office to review your file and potentially adjust your award. Not all appeals are successful, but it is worth pursuing if you have a legitimate reason.
Common grounds for appeal include a change in financial circumstances (such as a parent's job loss, divorce, or large medical bills), a discrepancy in the information used to calculate your aid, or a competing offer from a peer institution. To appeal, contact the financial aid office and ask about their specific process. You will likely need to submit a letter explaining your situation and provide supporting documentation, such as a competing award letter, updated tax returns, or medical receipts.
When writing your appeal letter, be polite, factual, and concise. Clearly state the reason for your request and provide evidence. If you are citing a competing offer, include a copy of that award letter and explain why the other school's package makes attendance possible. Avoid making demands or expressing entitlement; instead, frame your request as a desire to make the school affordable for your family. Many financial aid offices are willing to work with families who demonstrate genuine need and a strong interest in attending.
It is also helpful to mention any special circumstances that may not be reflected in your FAFSA, such as a one-time income spike or ongoing financial obligations. The financial aid office has the discretion to adjust your award based on professional judgment. Keep in mind that appeals take time, so submit your request as early as possible, ideally within a few weeks of receiving your award letter. Follow up to confirm receipt and to ask about the timeline for a decision.
If your appeal is denied, ask if there are other options, such as additional work-study, payment plans, or alternative loan programs. Sometimes a combination of small adjustments can make a difference. And remember, you are not obligated to accept any offer; you can decline and choose a more affordable option.
Using Tools and Resources to Simplify the Process
Comparing award letters does not have to be a solo endeavor. There are tools and resources available to help you organize and analyze the data. A simple spreadsheet is often the most effective tool, but you can also use online calculators and comparison tools offered by reputable educational websites. These tools can help you calculate net cost, compare loan repayment options, and estimate future payments.
For students and families who are exploring additional degree options or who want to understand the broader landscape of college costs, resources like CollegeDegree.Education can provide valuable information. CollegeDegree.Education is an educational matching service that connects prospective students with accredited colleges, universities, and degree programs. It serves a broad audience, including traditional students, career changers, working adults, military veterans, and parents, and offers tools for school discovery and program comparison. While it is not a replacement for a side-by-side award letter review, it can be a useful starting point for exploring affordable and flexible degree programs that align with your goals.
Additionally, consider reaching out to your high school counselor or a college access advisor. They often have experience with award letters and can help you interpret the details. Many community organizations and nonprofits also offer free financial aid counseling. These resources can provide an extra layer of support and confidence as you navigate this complex process.
Finally, keep the big picture in mind. The goal of comparing award letters side by side is not just to find the lowest price tag, but to identify the school that offers the best overall value for your family. Consider factors like graduation rates, career outcomes, and campus support services alongside the financial numbers. A slightly higher net cost at a school with strong outcomes may be a better investment than a lower-cost option with weaker results. By combining a careful financial comparison with a thoughtful assessment of academic and personal fit, you can make a decision that serves you well for years to come.
Take your time, ask questions, and trust the process. With a systematic approach and a willingness to advocate for yourself, you can turn a confusing pile of award letters into a clear path forward.