
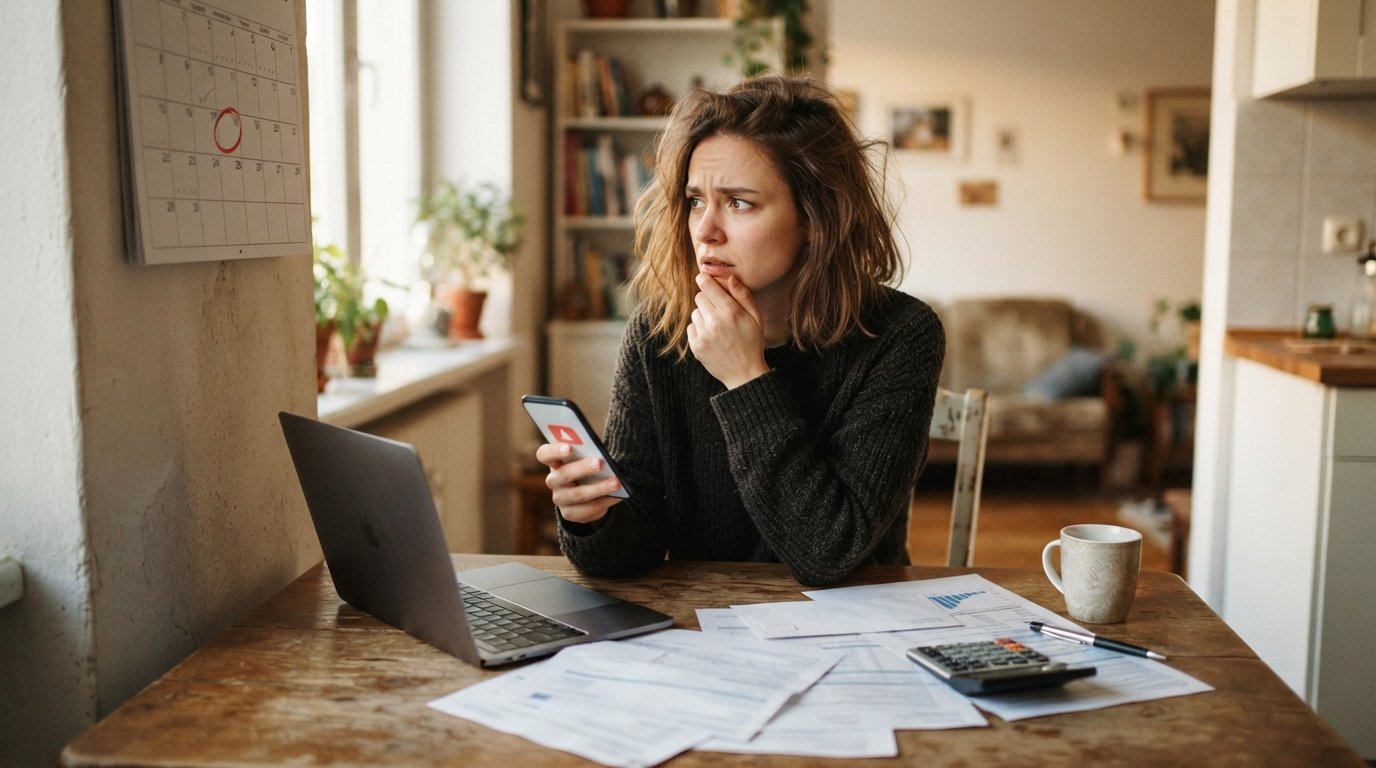
IDR Recertification Deadlines: What Happens If You Miss One
Missed your income driven repayment recertification deadline? Learn the real consequences and how to fix them fast. Call 8772187081 for guidance.
By Sophia Clark
Missing an income driven repayment (IDR) recertification deadline can quietly undo years of progress on your student loans. Your monthly payment can jump from a few dollars to hundreds, unpaid interest can capitalize, and in some cases you can lose credit toward forgiveness. The good news is that deadlines are predictable, the fixes are usually within reach, and a little planning can keep a small paperwork oversight from turning into a five-figure problem.
This guide walks through how IDR recertification works, when your deadline actually falls, exactly what happens if you miss one, and the fastest ways to recover. It is written for borrowers and families navigating federal student loans, and it pairs well with our broader walkthrough of student loan repayment options if you are still comparing plans.
How IDR Recertification Works and Why Deadlines Matter
Income driven repayment plans, including SAVE (currently in transition), Income Based Repayment (IBR), Pay As You Earn (PAYE), and Income Contingent Repayment (ICR), set your monthly bill based on your income, family size, and in some cases your spouse's income. That calculation is not permanent. The Education Department requires you to refresh, or "recertify," that information on a schedule so your payment reflects your current situation.
For most borrowers, recertification is required every 12 months. Your servicer typically sends a notice about 90 days before the deadline, then reminders closer to the date. You can also recertify early at any time if your income drops, which is often the smartest move after a layoff, a reduction in hours, or a switch to a lower-paying job.
There is one major exception worth knowing: if you are on IBR and your original payment obligation was calculated under the 10-year standard plan, your payment does not reset upward even if your income rises. You still need to recertify to stay in the plan and to keep making qualifying payments toward forgiveness, but the ceiling protects you from a surprise spike.
Your specific deadline depends on your anniversary date, which is tied to when you entered the plan or last recertified. You can find it on your servicer's website, in your annual notice, or by calling your servicer directly. Treat that date the way you would a tax deadline: it is fixed, it is enforceable, and late action has real costs.
When Your Recertification Deadline Actually Falls
Borrowers often assume the deadline is January 1 or tied to the tax filing season. It is not. Your deadline is personal, and it resets each time you successfully recertify. If you submit your paperwork in March one year, your next deadline is likely the following March, though servicers generally give a window rather than a single rigid day.
Here is how the timeline typically works:
- About 90 days before your anniversary, your servicer sends a recertification notice with your deadline and instructions.
- You submit income documentation (pay stubs, a tax return, or an IRS verification form) plus family size information.
- The servicer processes the request, usually within 7 to 15 business days, and sends a new payment amount.
- Your new payment takes effect on your next due date after processing, and your next 12-month clock begins.
Two timing quirks trip people up. First, if you file taxes jointly, your spouse's income generally counts unless you are on IBR, PAYE, or SAVE and file separately, so the documentation you submit matters as much as the deadline itself. Second, if you recertify very early, you may shorten your current payment window and reset your anniversary sooner than expected, which is fine but worth tracking.
If you are unsure which plan you are on or whether your spouse's income is included, your servicer can confirm the details in one call. It is far better to spend 20 minutes on the phone than to discover a missed deadline through a payment you cannot afford.
What Happens If You Miss an IDR Recertification Deadline
A missed recertification does not mean immediate default, but the consequences arrive quickly and can be expensive. Within a few weeks of your deadline passing, your servicer will move you to a standard 10-year repayment amount based on your full loan balance, with no income adjustment. On a $60,000 balance, that can mean a payment near $650 per month instead of the $80 you were paying.
Here are the main consequences in the order they typically hit:
- Payment shock: Your bill jumps to the standard plan amount, often several times your prior payment.
- Interest capitalization: On some plans, unpaid interest is added to your principal, so future interest accrues on a larger balance.
- Loss of forgiveness progress: Months spent in the wrong status may not count toward IDR forgiveness, and for Public Service Loan Forgiveness (PSLF), payments made at the wrong amount or under the wrong plan may not qualify.
- Collections risk: If you cannot pay the higher amount and stop paying entirely, you can eventually face delinquency and default, which brings wage garnishment, tax refund offsets, and credit damage.
The forgiveness angle is the most costly for long-term borrowers. If you are 8 years into a 20 or 25 year IDR forgiveness track, a missed deadline that pushes you out of qualifying status can add months or years to your timeline. For PSLF borrowers, the stakes are even higher because the program requires 120 qualifying payments, and payments made while you were not properly enrolled in a qualifying plan may be rejected.
There is one important safety net: the CARES Act and subsequent administrative changes created an on-ramp period during which missed payments are not reported to credit bureaus as delinquent. That protection is temporary and does not fix the recertification problem itself. It simply buys you time to correct the issue before credit damage occurs.
How to Recover After a Missed Deadline
The single most effective step is to recertify immediately, even if you are late. Servicers are generally required to accept late recertifications and to reinstate your income based payment once the paperwork is processed. In many cases, the higher payment applies only until the new calculation takes effect, and any overpayment can be adjusted on future bills.
Follow these steps in order:
- Log into your servicer account and confirm your current plan status and deadline.
- Submit a new IDR application with current income and family size documentation right away.
- Ask specifically whether you can be placed in a forbearance while the application processes, so you are not billed the standard amount in the meantime.
- Request a retroactive adjustment if you believe the higher payment was applied in error or should have been lower based on your actual income.
- If forgiveness credit was affected, ask for a payment count review, especially if you are pursuing PSLF.
If your income has dropped since your last certification, recertifying now can actually lower your payment below what it was before the missed deadline, turning a mistake into a reset. If your income has risen, you may still benefit from recertifying promptly because the alternative, staying on the standard plan amount, is almost always more expensive.
Borrowers who are struggling to navigate servicer transfers, plan changes, or conflicting information should consider free resources. The Federal Student Aid Information Center, state attorney general student loan units, and nonprofit counselors can help you escalate unresolved issues. If you are researching degree programs and want to understand how borrowing decisions today affect repayment later, adult learners can evaluate accredited options and cost data through resources like DegreesOnline.Education, which helps working professionals compare programs before taking on debt.
How to Avoid Missing Your Recertification Ever Again
Prevention is mostly about systems, not memory. Set a calendar reminder 120 days before your anniversary date, then a second one at 60 days and a third at 30 days. Add your servicer's name and phone number to the reminder so you can act without hunting for information.
Other habits that help:
- Recertify as soon as your servicer opens the window rather than waiting for the deadline.
- Keep digital copies of pay stubs, tax returns, and family size documentation in one folder.
- Update your address, email, and phone number with your servicer so notices do not get lost.
- Check your loan status every few months, especially after a servicer transfer.
- If your income changes significantly, recertify early instead of waiting for the annual date.
Married borrowers should also revisit their filing status each year. Filing separately can lower an IDR payment substantially on some plans, but it can raise your tax bill. Run the numbers both ways before you file, because the choice locks in for the year and directly affects your recertification result.
Key Takeaways for Borrowers
IDR recertification deadlines are not optional, but they are manageable. The worst outcomes, payment spikes, capitalized interest, and stalled forgiveness progress, almost always stem from inaction rather than from the deadline itself. Borrowers who recertify promptly, even late, usually restore their original payment within a few weeks.
If you take one thing from this guide, make it this: know your anniversary date, respond to servicer notices, and recertify the moment your income changes. Those three habits protect your monthly budget and keep your forgiveness timeline intact. And if you are still in the planning stage, understanding repayment rules before you borrow is the most powerful cost control tool you have.