
What Happens to Financial Aid If You Drop Below Full Time
Dropping below full time can shrink your Pell Grant, pause your loans, and jeopardize scholarships. See what happens to financial aid and how to protect it.
By Sophia Clark
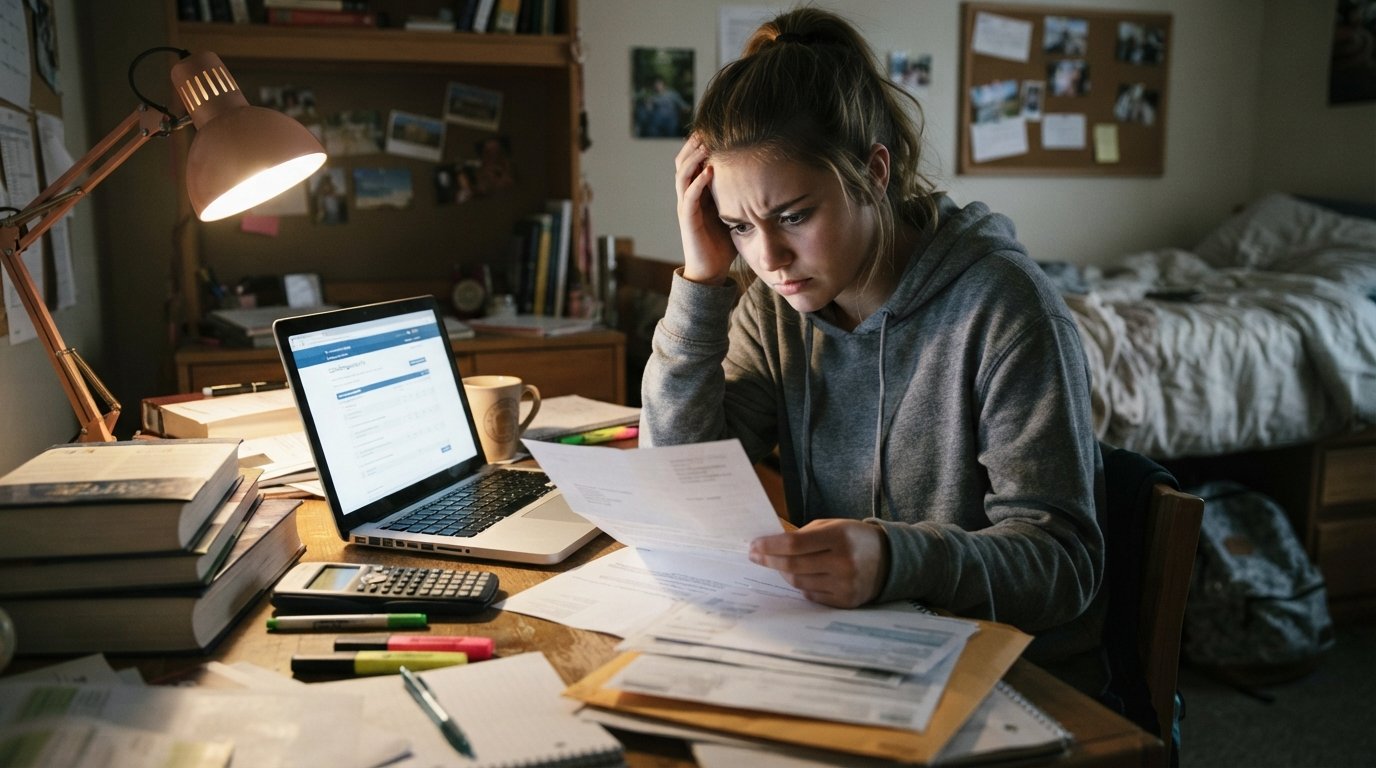
You are three weeks into the semester and the calculus is brutal: the chemistry lab consumes six hours a week, your part-time job just cut your hours, and the commute is eating your study time. Dropping a course feels like the obvious fix. But before you click that withdrawal button, you need to understand a hard truth about college financing: your financial aid package was built on an assumption about how many credits you would carry. Change that number, and the money can change with it. In many cases, dropping below full-time enrollment triggers a chain reaction that touches your grants, your loans, your scholarships, and even your future eligibility for aid. This guide walks through exactly what happens to financial aid if you drop below full time enrollment, so you can make the decision with your eyes open rather than learning the consequences from a surprising tuition bill.
Why Enrollment Status Matters More Than Most Students Realize
Financial aid is not a lump sum that follows you around regardless of what you do. It is a set of calculations tied to your enrollment intensity, which is the percentage of full-time study you are carrying in a given term. The federal government, state agencies, and individual colleges each run their own versions of this math, and each can respond differently when your credit load shrinks. Full-time status is typically defined as 12 or more credit hours per semester at the undergraduate level, though some schools use different thresholds for summer terms, mini-mesters, or graduate programs.
The first concept to understand is Satisfactory Academic Progress, usually shortened to SAP. Every school that receives federal aid must publish standards for pace, GPA, and maximum timeframe, and most schools measure pace in credit hours attempted versus completed. Dropping a class after the add/drop window can turn a completed course into a withdrawal, which counts as attempted but not completed. Do that often enough and your completion rate falls below the school's threshold, which can put you on financial aid warning or suspension even if your grades are fine. The second concept is enrollment intensity itself: many aid programs pay out on a sliding scale that shrinks as your credit hours shrink. Together, SAP and enrollment-intensity rules explain most of the unpleasant surprises students encounter after reducing their schedules.
There is also a timing dimension that matters enormously. Dropping a course during the add/drop period usually erases it from your record entirely, with no aid consequences. Dropping after the add/drop window but before the withdrawal deadline creates a W on your transcript and can affect both SAP and the current term's aid. Withdrawing after the school's aid recalculation date, or simply stopping attendance without formally withdrawing, is where things get genuinely messy. The lesson: the calendar is as important as the credit count.
How the Pell Grant Responds When You Drop Credits
The Pell Grant is the largest need-based federal grant for undergraduates, and it is the program most directly sensitive to part-time status. Pell awards are calculated using enrollment intensity, which the Department of Education defines as the percentage of full-time enrollment you are attending. If you are enrolled full time, you receive 100 percent of your scheduled Pell award for the term. At three-quarter time (typically 9 to 11 credits), you receive 75 percent. At half-time (6 to 8 credits), you receive 50 percent. Below half-time, you may receive 25 percent or nothing at all, depending on the school's packaging and your specific situation.
This proration is not retroactive in the way many students fear, but it is recalculated. If you drop from 12 credits to 9 credits early in the term, your school must recalculate your Pell eligibility based on the new enrollment intensity, which usually means a reduced disbursement or a repayment obligation for the difference if funds were already released. If you drop from 12 credits to 6 credits, the reduction is steeper. The good news is that Pell is generally more forgiving than loans: you do not have to repay grant funds you were eligible for at the time of disbursement, but you may owe back the portion that exceeded your recalculated eligibility.
There is a second Pell issue that catches students off guard: lifetime eligibility. Pell recipients are limited to the equivalent of 12 full-time semesters, and part-time enrollment consumes that limit more slowly, which is actually a benefit of dropping below full time. However, the flip side is that part-time enrollment stretches your time to degree, and if you are close to the lifetime limit, a reduced schedule can leave you without Pell support before you finish. Run the numbers with your financial aid office before assuming part-time study is the cheaper path.
Federal Student Loans: Half-Time Status and Proration
Federal student loans behave differently from Pell Grants, and the differences matter. Direct Subsidized and Unsubsidized Loans require at least half-time enrollment for disbursement. If you drop below half-time, you generally lose eligibility for new loan disbursements in that term, and your existing loans enter their grace period, which is the six-month window before repayment begins. That grace period is a one-time benefit per loan: if you use it now and return to school later, you may not get a fresh six months when you leave again.
For borrowers who remain at least half-time but below full-time, loan proration may apply. Annual loan limits are set for full-time study, and schools are required to prorate Direct Loan amounts when a student's final period of enrollment is shorter than a full academic year. The same logic can apply when you reduce your credits mid-term: your school may need to recalculate your cost of attendance and your loan eligibility, which can reduce the amount you can borrow for the remainder of the year. Parent PLUS loans and Grad PLUS loans are also tied to enrollment status and cost of attendance, so a reduced schedule can shrink the borrowing ceiling for your family as well.
The most dangerous loan scenario is the unofficial withdrawal. If you stop attending classes without formally withdrawing, federal rules require your school to treat you as having withdrawn, and you may be subject to the Return of Title IV Funds calculation. Under this rule, the school and the government can claw back a portion of the aid that was disbursed, and you can end up owing the school directly. This is why you should never simply stop going to class: always complete the formal withdrawal paperwork, even if it feels bureaucratic.
Scholarships and Grants With Full-Time Requirements
Private scholarships, institutional grants, and state grant programs are where full-time requirements bite hardest, because each program writes its own rules. Many merit scholarships awarded by colleges require recipients to maintain full-time enrollment, often defined as 12 or more credits, and some require 15 credits to stay on a four-year graduation track. Dropping to 9 credits can put such a scholarship on probation or trigger outright loss, and the appeals process varies widely by school.
State grant programs are another frequent trap. Several states tie their need-based grants to full-time enrollment, and a student who drops below the threshold can lose the entire state award for the term, not just a prorated portion. Outside scholarships from community foundations, employers, and professional associations often carry similar language in their award letters. The practical takeaway is that you cannot assume one rule covers everything: Pell, Direct Loans, state grants, institutional aid, and private scholarships each have their own enrollment definitions and their own recapture rules.
If you are planning to study abroad or participate in an exchange program, enrollment rules can get even more complicated, because host institutions may report credits on a different system. Our guide on how to fund your study abroad with scholarships and financial aid explains how to keep your aid intact when your credit load is measured in a foreign system.
What to Do Before You Change Your Enrollment Status
The single most important step is to talk to your financial aid office before you drop, not after. Aid counselors can run a personalized calculation showing exactly how your Pell, loans, state grant, and institutional scholarships would change at 9 credits versus 6 credits versus 3 credits. That conversation takes twenty minutes and can save you thousands of dollars. Bring your award letter and a list of every outside scholarship you receive, because the counselor will not automatically know about awards that do not run through the school.
Beyond that conversation, work through a structured checklist so nothing slips through the cracks:
- Confirm the school's official add/drop and withdrawal deadlines, and note which date triggers an aid recalculation.
- Ask the financial aid office for a written estimate of your revised Pell, loan, and grant eligibility at your planned credit load.
- Contact each scholarship provider directly to ask whether part-time status affects your award and whether an exception or appeal exists.
- Review your Satisfactory Academic Progress standing, including your completion rate, before adding another withdrawal to your record.
- Check whether your health insurance, campus housing, or veterans benefits depend on full-time status, since these can be affected independently of financial aid.
After you have that information, compare the total cost of each option rather than just the tuition line. Dropping to part-time may reduce your immediate bill but extend your time to degree by a semester or more, and each extra semester carries its own tuition, fees, and living costs. Sometimes the cheaper-looking choice is actually the more expensive one over the full program.
Alternatives Worth Considering First
Before you drop a course, ask whether a less damaging option exists. A course swap, where you drop one class and add another of equal credits during the add/drop window, usually has no aid impact at all. A late-start or mini-mester course can restore your credit count mid-term. Some schools allow an approved medical or emergency withdrawal that carries special aid protections. And if the problem is a single difficult class, a tutoring center, a study group, or a conversation with the professor about a grade replacement policy may solve the issue without touching your enrollment status. The goal is to protect both your transcript and your aid package at the same time.
Long-Term Consequences for Your Aid Eligibility
Dropping below full time is not just a one-semester event. Every withdrawal stays on your transcript and feeds into your SAP calculation for future terms, and repeated withdrawals can push your completion rate below the school's minimum even if your GPA remains strong. Students who fall onto financial aid warning and then fail to recover can lose federal aid entirely until they appeal or pay out of pocket to raise their completion rate. That is a hard hole to climb out of, and it is the reason aid offices treat repeated schedule reductions as a red flag.
There is also a career-planning dimension that students often overlook. Extended time to degree delays your entry into the workforce, which affects earnings, loan repayment timelines, and even eligibility for certain internships and licensure programs that require full-time enrollment in their final year. If you are using college as a launchpad into a specific occupation, it helps to understand the credential path and hiring expectations early. Resources such as Careers.org outline the degrees, licenses, and training that different professions require, which can help you judge whether stretching your timeline is a minor inconvenience or a real obstacle. For most students, the right move is to reduce risk rather than reduce credits: keep your load manageable, use support services, and only change enrollment status after you have confirmed exactly how your aid will respond.
The bottom line is that financial aid and enrollment status are tightly linked, and the link runs through Pell proration, loan half-time rules, scholarship terms, and Satisfactory Academic Progress. None of these rules is designed to punish you, but all of them will apply whether or not you knew about them. A short conversation with your aid office and a written estimate of your revised package turn a scary unknown into a manageable decision. Protect your aid by planning the change instead of letting the change happen to you.