
Comparing Two College Financial Aid Offers Side by Side
Compare two college financial aid offers side by side to see the real four-year net cost and avoid overpaying by thousands.
By Emily Wilson
Two thick envelopes arrive on the same afternoon, each with a different college logo and a different set of numbers. One school looks generous at first glance because the total aid figure is larger, but the other charges less for housing and requires no unpaid campus work hours. Families who compare only the headline aid number often choose the package that actually costs more over four years. The only reliable way to decide is to place both offers on the same page, normalize every number to a common standard, and evaluate what each package really asks your family to pay and to do.
This process matters because financial aid letters are not standardized. One college may list a Federal Direct Subsidized Loan inside the aid total, while another lists loans separately. One may include a work-study estimate that your student may never earn. Comparing offers requires stripping out the marketing and rebuilding each one on equal footing.
Normalize Every Offer to Four-Year Net Cost
The single most useful number in any comparison is net cost: the total price of attendance minus grants and scholarships that do not need to be repaid. Most aid letters show a one-year net cost, or they bury it under a list of line items. Converting each offer to a four-year figure exposes differences that a single-year view hides, especially when schools front-load grants in the first year and reduce them later.
Start by collecting four numbers from each offer: total cost of attendance, gift aid (grants and scholarships), loan amounts, and work-study. Then apply a simple formula to each school. Multiply the annual net cost by four, but adjust for expected tuition increases and for any grant that is renewable only under conditions such as maintaining a GPA. If a school's grant drops after year one, build that decline into the calculation. The goal is not mathematical perfection; it is a realistic four-year estimate that lets you compare apples to apples.
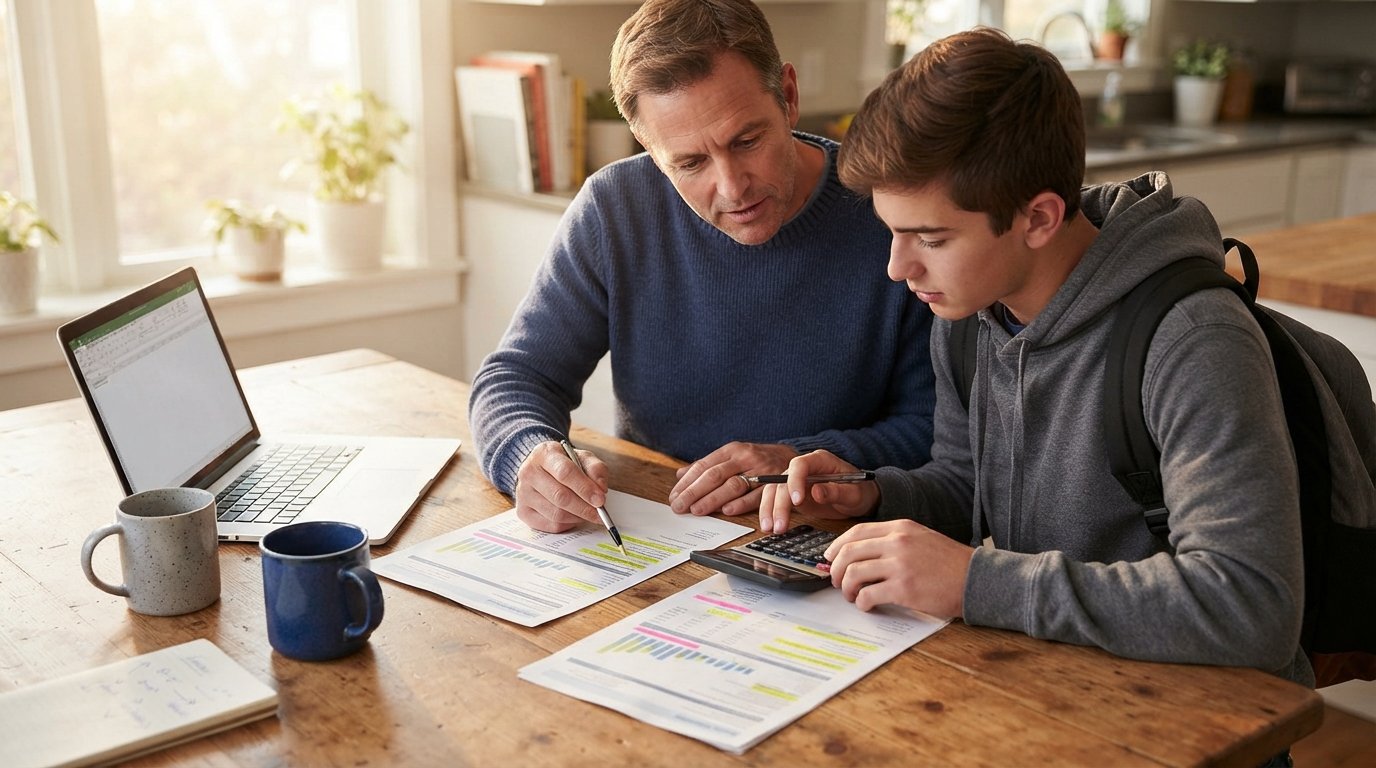
A side-by-side worksheet makes the comparison visual. List each school as a column and each cost category as a row. Include tuition, mandatory fees, housing, meal plan, books and supplies, transportation, and personal expenses. Then subtract gift aid only, and record loans and work-study separately below the line. The bottom row is your true out-of-pocket figure. For a deeper walkthrough of how to parse each line item on an award letter, see this guide on how to read college financial aid award letters side by side, which covers the terminology and traps in detail.
Separate Grants, Loans, and Work-Study in Each Package
Not all aid is equal. A package that is heavy on loans is not comparable to a package that is heavy on grants, even if the totals match. Grants and scholarships are gifts: they reduce your cost permanently. Loans must be repaid with interest, and every dollar borrowed today reduces your student's future take-home pay. Work-study is earned income, which means the student must find an eligible job and work the hours to receive it.
When you compare two offers side by side, classify each component before you add anything up. A useful framework is to sort every dollar into one of three buckets and keep the buckets separate throughout your analysis.
- Gift aid: federal Pell Grants, state grants, institutional scholarships, and private awards that require no repayment.
- Self-help aid: federal student loans, parent PLUS loans, and any private loan included in the package.
- Earned aid: Federal Work-Study or campus employment estimates that depend on the student actually working.
After sorting, ask which school offers the higher proportion of gift aid. A package of $30,000 in grants is worth far more than a package of $30,000 split between grants and loans. Also check whether grants are need-based or merit-based, and whether they are renewable for all four years. Some institutional grants carry GPA requirements or enrollment minimums that can cause them to disappear after a rough semester. If a grant is conditional, treat part of it as at risk in your four-year calculation.
Loans deserve a second look for another reason: they are often listed inside the aid total to make the package appear larger. A school that includes $5,500 in federal loans may look more generous than a school that excludes loans from its aid figure, even when the second school is actually cheaper. Always recalculate each offer using gift aid only, then compare what remains. This single adjustment frequently reverses the apparent winner.
Appeal Offers and Ask Competing Schools to Match Aid
Financial aid offers are not always final. Many colleges have a formal reconsideration process, and some will adjust a package when presented with a competing offer from a similar school. This practice, sometimes called professional judgment or a competitive review, is most effective when you approach it with documentation and a clear, specific request rather than a general plea for more money.
The strongest appeals follow a simple sequence. First, identify a concrete reason your situation warrants review: a competing offer from a peer institution, a change in family income, unusual medical expenses, or a one-time financial event not reflected in the FAFSA. Second, gather the paperwork that supports the claim, such as the competing award letter, pay stubs, or a letter explaining the changed circumstances. Third, contact the financial aid office in writing and ask for a specific adjustment, such as matching a grant or increasing institutional aid by a stated amount. Fourth, follow up politely and keep a record of every conversation.
Timing matters as much as the request itself. Aid offices are busiest between admission decisions and the enrollment deadline, and they often have limited flexibility late in the season. Begin the appeal as soon as both offers are in hand, and give the school at least two weeks to respond. When you present a competing offer, be transparent: schools can and do verify claims, and credibility is your most valuable asset in this conversation. For students still assembling their list of outside awards, resources such as Scholarship.Education can help identify additional scholarships that strengthen a package before the appeal window closes.
Timelines for Accepting and Requesting Reconsideration
Most colleges set a national reply deadline of May 1 for first-year students, though some schools use rolling deadlines or extend the date for students who request more time. Missing the deadline can cost your student the admission slot and the aid package together, so treat the reply date as a hard boundary. Build a calendar that lists each school's deadline, the date by which you must submit an enrollment deposit, and the date by which you must accept or decline the aid offer.
Reconsideration requests should be filed before you accept, not after. Once you commit and pay a deposit, your leverage drops sharply. A practical timeline looks like this: in early to mid-April, complete your side-by-side comparison and identify your top choice; by mid-April, submit appeals to any school whose offer you would accept if the aid improved; in the final week of April, compare any revised offers and make your decision; by May 1, accept one offer and decline the others in writing so that waitlisted students can benefit from released aid.
Keep copies of every document you send and receive. If a school revises an offer, confirm the new terms in writing, including whether the increase applies to all four years or only the first. A verbal promise from an aid counselor is helpful but not binding; the revised award letter is the document that counts. If your family's circumstances change after you accept, such as a job loss or a major medical expense, you can still request a review, though the available funds may be more limited.
Factor in Hidden Costs and Program Value
Net cost is the foundation of the comparison, but it is not the whole decision. Two schools with nearly identical four-year costs can differ sharply in transportation, housing availability, and the time required to finish a degree. A school that charges less per year but requires an extra semester to complete the program may cost more overall. Conversely, a school with a slightly higher net cost may offer co-op placements, paid internships, or accelerated pathways that reduce total expenses and improve outcomes.
Include these variables in your worksheet alongside the dollar figures. Estimate travel costs based on distance and how often your student will come home. Check whether the aid package assumes on-campus housing all four years, since off-campus rent can change the math. Look at four-year graduation rates for the specific program, not just the institution overall, because a longer time to degree multiplies every annual cost. Finally, weigh the strength of the program in your student's intended field: a modest difference in net cost is often worth accepting for a program with better career placement, but a large difference in debt should give any family pause.
When the numbers and the intangibles conflict, return to the four-year net cost figure and ask what monthly loan payment each option implies after graduation. That single question often clarifies which offer is genuinely affordable. Comparing two college financial aid offers side by side is ultimately an exercise in stripping away presentation and measuring what your family will actually pay, borrow, and earn. Families who do that work before the May 1 deadline consistently make decisions they do not regret.